Is Japan Back? Growth and Corporate Governance
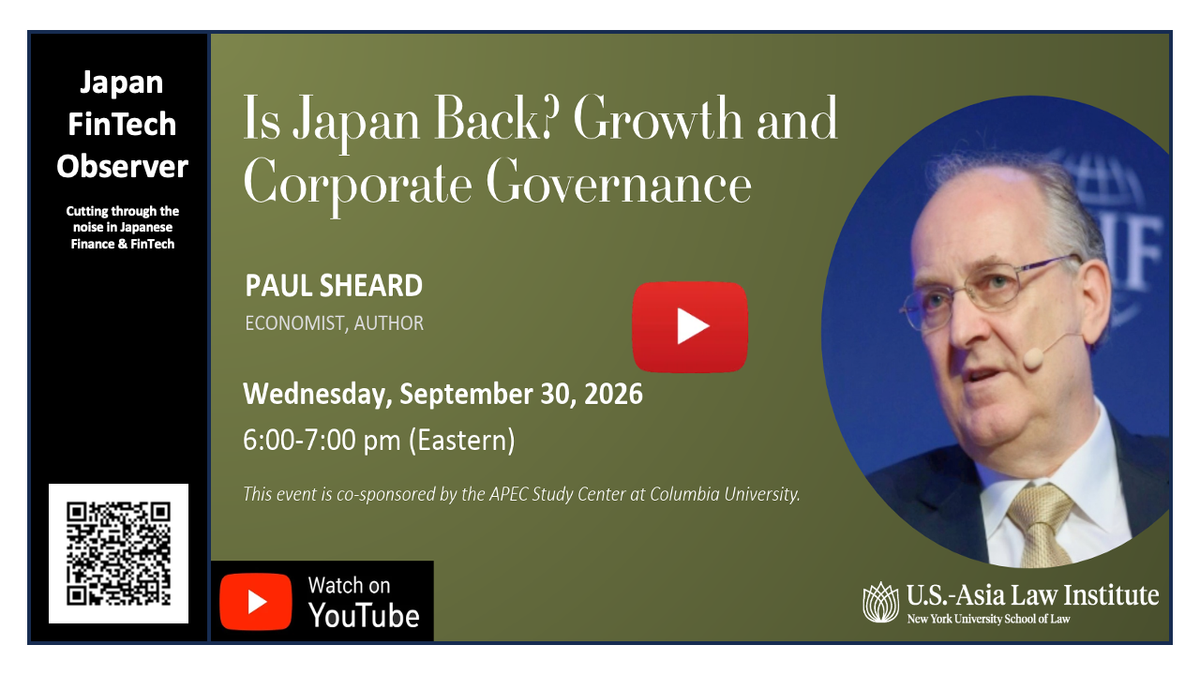
On September 30, 2026, Bruce Aronson (Head of the Japan Center at the US-Asia Law Institute, NYU Law) hosted Dr. Paul Sheard (prominent macroeconomist, former senior executive at S&P Global and Nomura Securities, and author of The Power of Money) to discuss Japan's most profound economic regime shift in three decades—transitioning from twenty-eight years of chronic mild deflation to sustained nominal growth, rising benchmark interest rates, and institutional corporate restructuring. Evaluating these structural dynamics is essential for global institutional investors, sovereign policymakers, and international trade analysts. The ongoing transformation spans monetary policy normalization, fiscal strategy, firm-level capital allocation, and household balance sheet rebalancing, offering vital insights into how advanced industrial economies can overcome persistent demographic headwinds and structural economic stagnation.
- Monetary Normalization & Deflation Exit
Japan has executed a definitive structural exit from the chronic deflationary regime that persisted from the second quarter of 1994 through 2022. During this period, the economy-wide GDP deflator fell by a cumulative 17%, whereas the equivalent US deflator expanded by approximately 54%. Spurred by post-COVID adjustments, yen depreciation, and global supply dynamics, Japan’s GDP deflator has rebounded by 17% since 2022, restoring overall price levels to their 1994 baseline. In response, the Bank of Japan (BOJ) terminated its aggressive Quantitative and Qualitative Monetary Easing (QQE) framework, raising its benchmark policy rate to 1.25%—its highest level in 31 years since 1995. With 10-year Japanese Government Bond (JGB) yields crossing 3%, monetary policy is transitioning from zero-peg accommodations toward market-based rate normalization. This regime shift replaces decades of economic "chill" with warm nominal GDP expansion, directly expanding corporate top-line revenues and boosting government tax collections. - Policy Continuity vs. Government-Led Industrial Strategy
Japanese economic strategy exhibits strong administrative lineage, originating within the Kasumigaseki bureaucracy—principally the Ministry of Economy, Trade and Industry (METI) and the Ministry of Finance (MOF)—in close coordination with business associations like Keidanren. Incoming LDP prime ministers traditionally rebrand these pre-existing bureaucratic plans into signature political slogans. While Abenomics (2012–2020) emphasized aggressive monetary expansion, flexible fiscal policy, and market-oriented corporate deregulation, the contemporary paradigm under "Sanaenomics" pivots toward a state-directed industrial policy framework. Operating under "responsible activist fiscal policy," this strategy targets 370 trillion yen in public-private investment by FY2040 across 17 target strategic sectors, 62 critical technologies and products, and 8 cross-sectoral challenges. By tightly integrating economic security, national defense, cyber capabilities, and supply chain resilience, the framework raises macro-structural critiques regarding whether government direction risks dampening private-sector market dynamism and resource allocation efficiency. - 35-Year Corporate Governance Evolution & Market Re-Rating
The dramatic rally in Japanese equities—highlighted by the Nikkei more than doubling and breaking all-time highs—is supported by a 35-year structural overhaul of corporate governance rather than short-term market speculation. Regulatory milestones include early 1990s asset management deregulation, the mid-1990s legalization of holding companies, share buybacks, treasury stock holding, and late-1990s consolidated accounting. Board structures have evolved from internal statutory auditors toward independent director committee systems (Audit, Nomination, and Compensation), with top-tier firms maintaining majority or half-independent boards. Concurrently, cross-shareholdings held by corporate insiders have inverted from 80% down to 20%, empowering arm's-length institutional investors who demand higher Return on Equity (ROE) and capital discipline. Foreign investors, holding 35% of Japanese equities, act alongside domestic regulators (TSE, FSA, METI) to pressure risk-averse management teams to optimize capital efficiency and return cash hoards to shareholders. - The Corporate Cash Surplus and Structural Capital Allocation Dilemma
Despite macroeconomic revival, Japan's corporate sector presents a primary structural bottleneck: massive cash accumulation on balance sheets. Japan maintains a structural current account surplus of 3% to 5.1% of GDP, representing a net national savings surplus exported globally. On a flow-of-funds basis, while the consolidated public deficit has narrowed to 1.3% of GDP in FY2025, the private sector holds a net savings surplus of 6.3% of GDP, with corporate retained earnings accounting for 4.4 percentage points and households 1.9 percentage points. Because private corporations save rather than fully invest or raise wages, capital allocation has become the central battleground. Private equity funds, activist investors, and regulatory Tokyo Stock Exchange (TSE) price-to-book ratio (PBR < 1.0) mandates are forcing management teams to deploy uninvested cash into high-return capex, wage increases, or share buybacks to recirculate capital back into the broader economy. - Demystifying Sovereign Debt Through Consolidated Accounting
Headline assessments citing Japan's gross public debt at 240% of GDP misinterpret sovereign default risk by evaluating fiscal liabilities in isolation. Analyzing the consolidated government balance sheet—combining the Ministry of Finance and the Bank of Japan—reveals structural stability. Through historical QQE operations, the BOJ purchased nearly 50% of outstanding JGBs, converting traditional fixed-income public debt into central bank commercial bank deposit reserves. These central bank liabilities face no traditional bond maturity schedules or default mechanics. Supported by world-leading net foreign asset holdings built over 45 consecutive years of current account surpluses, Japan remains the world's largest net creditor nation. Rising interest rates increase headline debt-servicing allocations, but these represent internal income transfers to domestic commercial banks and depositors rather than external default risks or national resource depletion.
These core takeaways demonstrate how high-level macroeconomic transformations and sovereign balance sheet structures interact directly with firm-level strategic choices and institutional policy frameworks.
1. Comparative Analysis of Macroeconomic Policy Frameworks: Abenomics vs. "Sanaenomics"
Japanese economic policy is characterized by structural continuity across Liberal Democratic Party (LDP) administrations. Rather than drafting economic programs in isolation, incoming prime ministers draw upon extensive strategic planning generated within the Kasumigaseki bureaucracy—principally METI, MOF, and the Cabinet Office—in close coordination with peak business federations such as Keidanren. These bureaucratic initiatives are packaged under signature political slogans to signal reform intent to domestic constituencies and global financial markets.
1.1 Historical Policy Lineage
The trajectory of contemporary Japanese growth strategies traces through sequential administrative reform pushes across four decades:
- 1980s (Nakasone Administration): Commissioned the Maekawa Report, authored by a former Bank of Japan governor, which established the early structural reform blueprint for domestic demand-led growth and economic opening.
- Mid-1990s (Hosokawa & Hashimoto Administrations): Prime Minister Hosokawa initiated systemic economic deregulation. Subsequently, Prime Minister Ryutaro Hashimoto launched the "Six Big Reforms"—encompassing financial, structural, administrative, fiscal, education, and social security reforms. A cornerstone was the "Financial Big Bang," initiating a multi-decade modernization of Japanese capital markets and financial segmentation.
- 2001 (Koizumi Administration): Advanced market-oriented structural reform centered on the privatization of the massive Postal Savings system (Yucho), directly executing the administrative reform agendas established during the Hashimoto era.
1.2 Deconstructing Abenomics (2012–2020)
Returning to office in December 2012, Prime Minister Shinzo Abe codified economic strategy into the "Three Arrows" framework:
- Aggressive Monetary Policy: The core macroeconomic engine, executed by BOJ Governor Haruhiko Kuroda beginning in April 2013 through Quantitative and Qualitative Monetary Easing (QQE).
- Flexible Fiscal Policy: Designed to pair monetary expansion with calibrated fiscal stimulus to prevent premature austerity while accommodating statutory tax adjustments.
- Growth Strategy / Structural Reform: Microeconomic initiatives covering labor market flexibility, corporate governance codes, deregulation, and "Womenomics."
The catalyst for this regime shift was a pivotal political sequence in late 2012. In August 2012, the ruling Democratic Party of Japan (DPJ) negotiated a deal with the LDP to pass legislation doubling the consumption tax from 5% to 10% in two stages (to 8% in April 2014 and 10% in October 2015). In exchange for LDP support in the upper house, Prime Minister Yoshihiko Noda agreed to dissolve the lower house, triggering the December 2012 general election where Abe won a decisive mandate. Because BOJ Governor Masaaki Shirakawa’s 5-year term expired in March 2013, Abe was positioned to appoint Kuroda, who launched unprecedented balance sheet expansion in April 2013 by purchasing JGBs at scale to shock the economy out of its deflationary mindset.
1.3 Deconstructing "Sanaenomics" & Growth Strategy
The policy paradigm under "Sanaenomics" adjusts both macroeconomic emphasis and microeconomic growth execution to operate within an inflationary environment:
- Macro Pillar: Combines "responsible activist fiscal policy"—utilizing state expenditure proactively—with explicit political preferences for low central bank interest rates. Proposed fiscal measures include a temporary two-year reduction of the consumption tax on food from 8% to 1%.
- Macro Policy Paradox: Uncoordinated fiscal expansion alongside BOJ rate normalization creates an inconsistent macroeconomic policy mix. If fiscal stimulus adds demand pressure while the central bank seeks to anchor inflation at 2%, the BOJ will be forced to execute higher interest rate hikes than would otherwise be necessary to maintain price stability.
- Micro / Growth Pillar: Shifts focus toward explicit state-directed industrial policy and economic security. The framework sets a target of 370 trillion yen in combined public-private investment by FY2040. The administrative architecture establishes 17 target strategic sectors, 62 critical technologies and products, and 8 cross-sectoral challenges, prioritizing national resilience, cyber security, defense infrastructure, and technological sovereignty.
1.4 Critical Assessment of Industrial Policy
Dr. Sheard highlights a fundamental macro-structural critique regarding the microeconomic orientation of Sanaenomics. While state-backed expenditure in defense, cyber capabilities, and strategic supply chains addresses legitimate geopolitical risks, establishing a Showa-era Kasumigaseki "control tower" to direct 370 trillion yen across 17 target sectors risks repeating historical industrial policy inefficiencies. In an advanced economy facing labor and resource constraints, sustainable economic dynamism depends on private corporate managers identifying market opportunities, executing restructurings, and reallocating capital efficiently, rather than relying on bureaucratic investment blueprints.
Transitioning from state-directed macro targets to market dynamism requires examining the microeconomic governance mechanisms that dictate firm-level capital allocation.
2. The Microeconomic Engine: Evolution of Corporate Governance and Capital Allocation
Firm-level corporate governance reform serves as the primary engine translating macroeconomic exit from deflation into sustainable equity value, foreign capital inflows, and efficient resource allocation.
2.1 35-Year Reform Timeline
The modernization of Japanese corporate governance is the product of continuous, incremental regulatory enhancements over three decades:
- Early 1990s (Asset Management Deregulation): The Ministry of Finance dismantled the traditional "convoy system," breaking the exclusive monopoly held by life insurance companies and trust banks over investment trusts and pension assets. Opening the market established a competitive asset management industry that actively scrutinizes corporate performance.
- Mid-1990s (Legalization of Holding Companies): Post-WWII bans on holding companies were repealed. Today, five of the top ten listed stocks in Japan operate under holding company frameworks (including two major banking groups, SoftBank Group, Recruit Holdings, and Kioxia Holdings). Holding company boards exercise top-tier fiduciary oversight, facilitating M&A, divestitures, and corporate restructurings.
- Late-1990s (Capital Flexibility & "Accounting Big Bang"): Regulatory reforms legalized share buybacks and allowed corporations to hold treasury stock, providing efficient mechanisms to return excess capital to shareholders. Concurrently, the "Accounting Big Bang" shifted reporting standards from parent-only financial statements to consolidated accounting, exposing hidden subsidiary losses and balance sheet inefficiencies.
- Early 2000s–Present (Board Structure Reforms): Corporate law transitioned away from reliance on internal statutory auditors (kansayaku)—who were historically company insiders—toward board systems featuring independent Audit, Nomination, and Compensation committees. Today, top-tier listed corporations maintain boards where at least half of the directors are explicitly designated independent outsiders.
2.2 The Inversion of Cross-Shareholdings
The structural anchor of traditional Japanese corporate defense—the cross-shareholding system (keiretsu interlocking stock ownership)—has collapsed. Thirty-five years ago, approximately 80% of corporate equities were held by friendly corporate insiders and financial institutions, leaving only 20% with arm's-length investors. Today, that structural ratio has inverted: insider cross-shareholdings have fallen to roughly 20%, while arm's-length institutional and retail investors hold 80%.
This structural shift from relational capital to arm's-length market discipline deprives management of insulated voting majorities. Boards face direct exposure to market demands regarding Return on Equity (ROE), capital allocation efficiency, and strategic portfolio optimization.
2.3 Foreign Investor Impact & Government Alignment
Foreign institutional ownership of Japanese equities has steadily expanded, reaching 35% of total market capitalization (up 4.5 percentage points over the past five years). Foreign investors act as active catalysts for capital discipline. Crucially, state institutions have aligned with global market standards:
- Tokyo Stock Exchange (TSE): Mandates explicit capital efficiency plans, pressuring listed firms trading below book value (PBR < 1.0) to optimize balance sheets.
- Financial Services Agency (FSA) & METI: Published updated guidelines on corporate takeovers and market stewardship, instructing management teams that uninvited activist or private equity bids must be evaluated on financial merit rather than summarily rejected.
2.4 Demographic Relief via Womenomics
Corporate structural optimization has countered ingrained institutional risk-aversion and cultural biases toward structural pessimism. Despite overall population contraction, labor force participation has remained resilient due to the structural entry of women and older workers. Accelerated during the Abe administration under "Womenomics," female labor force participation experienced a sharp structural upward inflection, expanding workforce capacity and helping buffer corporate operations against demographic decline.
Optimizing microeconomic capital allocation leads directly into the broader macroeconomic mechanics governing inflation, wage formation, and household wealth.
3. Macroeconomic Realities: Deflation Exit, Nominal Growth, and the Household-Corporate Nexus
Japan's transition from a 28-year deflationary mindset (1994–2022) to an inflationary, nominal growth regime represents a fundamental behavioral shift across corporate management, labor, and domestic households.
3.1 Deflation Mechanics & Deflator Analysis
The depth of Japan's structural stagnation is captured by the GDP deflator—the comprehensive measure of economy-wide inflation encompassing consumer spending, residential housing, and capital investment. Between its peak in the second quarter of 1994 and its trough in 2022, Japan’s GDP deflator dropped by a cumulative 17%. Over the exact same period, the US GDP deflator expanded by approximately 54%.
Continuous price contraction generated a persistent psychological "chill" across the economy:
- Corporations delayed capital expenditure and wage increases, anticipating lower input costs and sluggish future demand.
- Consumers postponed purchases, rationalizing that cash would gain purchasing power over time.
- Nominal GDP stagnated, directly suppressing top-line corporate revenues, equity valuations, and tax receipts.
3.2 Post-2022 Inflation & Wage Dynamics
Since the second quarter of 2022, post-COVID supply adjustments, global price shifts, and a weaker yen generated an inflationary breakout. The GDP deflator rebounded by 17%, fully restoring price levels to 1994 baselines and placing Japan into nominal GDP expansion.
Initial post-2022 inflation outpaced nominal wage adjustments, leading to temporary real wage contraction that suppressed domestic consumption. To prevent a return to deflation, the government and the BOJ utilized the annual spring Shunto labor negotiations to encourage major corporations to institute structural wage increases. As corporate managers accepted that inflation was enduring, base pay hikes accelerated, re-establishing positive real wage dynamics and aligning wage formation with the central bank’s 2% inflation target.
3.3 Household Wealth & Deposit Conversion
Japanese households hold vast financial wealth, approximately 50% of which sits in liquid bank deposits or cash. During deflation, holding cash was rational: a 0% nominal yield combined with 1% to 2% annual price declines generated a positive real return of 1% to 2% with zero principal risk.
In an inflationary regime with 2% to 3% price growth, idle bank deposits suffer real purchasing power erosion. To transition household savings into productive assets, the government expanded the NISA (Nippon Individual Savings Account) program, offering tax-exempt structures to encourage retail investment in equity markets. This conversion of domestic household savings into equity capital provides sustained retail support for Japanese asset markets.
3.4 The K-Shaped Recovery Dilemma
The exit from deflation presents political and social challenges. While corporate revenues, tax collections, and equity indexes have surged, households without equity portfolios face higher cost-of-living expenses. Technocratic inflation targets (2% baseline stability) conflict with public perception, as consumers view price increases as reduced purchasing power rather than economic health. Managing this tension requires sustained real wage expansion to ensure the benefits of nominal growth extend beyond corporate balance sheets to the broader electorate.
This balance between household purchasing power and corporate cash accumulation leads directly to questions surrounding national fiscal sustainability, public debt, and Japan's external balance sheet.
4. Sovereign Debt, Fiscal Dynamics, and Japan’s External Balance Sheet
Conventional sovereign risk models often apply simplified debt-to-GDP metrics to assess fiscal sustainability. Applied to Japan, these framework models misdiagnose risk by treating public balance sheets in isolation from central bank operations and national net asset positions.
4.1 Deconstructing the "Debt Elephant"
Headline statistics frequently emphasize Japan’s gross public debt ratio of roughly 240% of GDP. However, evaluating sovereign risk requires a consolidated balance sheet approach, treating the Ministry of Finance and the Bank of Japan as a single consolidated public entity:
- Through decade-long QQE operations, the BOJ purchased approximately 50% of all outstanding JGBs.
- When the BOJ purchases JGBs from the secondary market, it replaces fixed-income bond liabilities issued by the MOF with central bank reserves (commercial bank deposit accounts held at the central bank).
- Consolidated public debt owed to arm's-length market participants is effectively reduced by half. Central bank reserves are monetary liabilities that never face traditional bond maturity repayment schedules or default mechanics.
4.2 Yield Normalization Dynamics
As the BOJ normalizes monetary policy, 10-year JGB yields have adjusted upward past 3%. Rather than indicating a bond market disruption, yield movements represent a return to market pricing. Historical context demonstrates that current yields remain modest; for example, in 1995, 10-year JGB yields stood at 4.5% prior to QQE implementations that pegged yields near 0%.
The BOJ estimates its neutral interest rate lies between 1.1% and 2.5%. With benchmark policy rates at 1.25%, policy rate adjustments up to 2.0% with a standard term premium represent standard macroeconomic normalization. While higher yields increase formal debt-servicing allocations, these payments represent interest transfers from the government to domestic commercial banks and depositors rather than external capital drain.
4.3 External Balance Sheet & Savings Surplus
Japan’s fiscal position is anchored by its position as the world's largest net creditor nation, supported by 45 consecutive years of current account surpluses (~3% to 5.1% of GDP). National flow-of-funds metrics confirm structural financial stability:
- Consolidated Public Deficit: Narrows to 1.3% of GDP in FY2025 (compared to historical deficits of 5% to 8%).
- Private Sector Surplus: Generates a net savings surplus of 6.3% of GDP after accounting for domestic capital investments.
- Sectoral Breakdown: Corporate retained earnings generate 4.4 percentage points of the surplus, while households generate 1.9 percentage points.
Because the domestic private sector generates excess savings (6.3% of GDP) that easily absorb the public deficit (1.3% of GDP), Japan funds its public debt internally while exporting remaining capital abroad as a net current account surplus (5.1% of GDP).
4.4 Corporate Cash Accumulation & Macro-Structural Bottlenecks
The primary macroeconomic bottleneck is not sovereign debt default, but the persistent hoarding of capital within the corporate sector. In national accounting identities, when private corporations hold surplus savings equal to 4.4% of GDP rather than investing in domestic capex or expanding payrolls, the public sector is forced to run fiscal deficits to absorb excess national savings and prevent broader economic contraction. Uninvested corporate cash drags directly on long-term potential growth.
Furthermore, as part of past QQE operations, the central bank acquired substantial equity holdings through ETF purchases, currently valued between 30 trillion and 60 trillion yen. As the government narrows its fiscal deficit, administrative policy relies on market discipline—including private equity funds, activist investors, regulatory pressure from the TSE, and share buyback programs—to force corporate management to deploy cash reserves into productive domestic investment, wage increases, or equity buybacks.
5. Conclusion: Regime Shift Confirmed
The empirical evidence confirms that Japan has entered a structural economic regime shift. The exit from a 28-year deflationary environment, combined with the inversion of cross-shareholdings, independent board oversight, rate normalization, and robust current account surpluses, demonstrates that Japan's macroeconomic revival is anchored in permanent institutional reform. Driven by structural capital reallocation and corporate governance modernization, Japan's economic transformation provides a sustainable foundation for long-term nominal expansion.
 Norbert Gehrke